
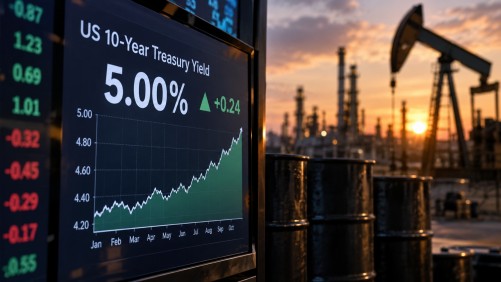
The yield on the benchmark 10-year US Treasury bond has reached 5% for the first time since 2023, reflecting a significant shift in global financial markets. This surge, driven by a sharp sell-off in bonds, coincides with escalating oil prices and mounting inflationary fears. Earlier this year, the yield had dipped to around 4% but has been on an upward trajectory following the onset of the US-Israeli conflict with Iran in February. The last time yields were at this level was in October 2023, marking a critical development for borrowing costs across the globe.
Global oil markets are also experiencing turbulence, with Brent crude surpassing $108 a barrel. This increase follows a series of attacks that have disrupted Saudi Arabia’s energy infrastructure, exacerbating tensions in the Middle East. The closure of a vital east-west crude pipeline in Saudi Arabia due to drone strikes has heightened concerns about global oil supply stability. Compounding the situation are attacks linked to Iran-aligned Houthi forces and rising tensions around the strategically critical Bab al-Mandab Strait.
The situation has further deteriorated as Gulf states have delayed negotiations with Tehran over a provisional shipping route through the Strait of Hormuz, a crucial passage for the world’s oil and gas shipments. These developments have intensified inflationary pressures, raising questions about future interest rate directions. Both the US Federal Reserve and the Bank of England are set to make key interest-rate decisions soon, which are being closely watched by investors.
The climb in US Treasury yields holds significant implications for global financial markets, as the 10-year Treasury is a widely regarded benchmark for borrowing costs worldwide. Rising yields could lead to increased financing expenses for governments, businesses, and households globally. Additionally, Europe’s bond markets have seen similar trends, with UK long-term government borrowing costs reaching historic highs. The combination of soaring energy prices and renewed geopolitical tensions suggests that central banks might need to maintain stringent monetary policies for an extended period.
Throughout the year, oil prices have been notably volatile. From a pre-conflict benchmark of around $72 a barrel, Brent crude prices peaked at approximately $126 in April, before moderating in the summer amid hopes for a ceasefire. However, as hostilities have intensified and diplomatic efforts have faltered, prices have surged once more, topping $100 a barrel. This volatility has sparked fresh concerns over inflation, interest rates, and the broader implications of prolonged disruptions to global energy and trade routes.